Welcome to GreenMore
Welcome to GreenMore
Most large-scale battery storage operating in the United States earns its core revenue from electricity price arbitrage — charging when wholesale prices are low, often midday amid solar oversupply, and discharging during higher-price evening hours. According to the U.S. Energy Information Administration (EIA), arbitrage was the leading primary use of utility-scale batteries in 2024, followed by frequency regulation and renewable-energy integration.
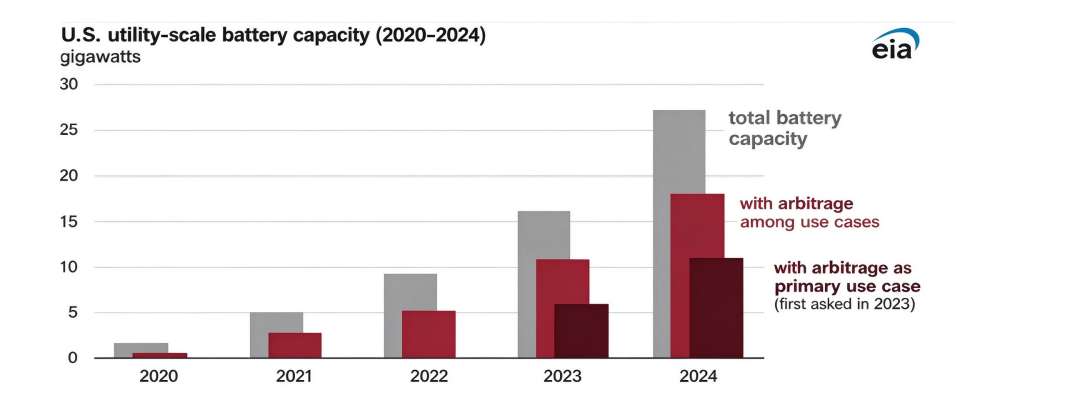
The EIA collects annual data from utility-scale storage facilities of 1 MW or larger through its Annual Electric Generator Report (Form EIA-860). Beginning with the 2023 survey, operators have been asked to identify the primary use case of each battery system, which makes the revenue picture clearer than older data that recorded every use without ranking them.
| Metric (end of year) | 2023 | 2024 |
|---|---|---|
| Total utility-scale battery capacity | About 16 GW | About 26 GW |
| Capacity with arbitrage among its uses | Not separately published | About 18 GW (66%) |
| Capacity primarily used for arbitrage | About 10.5 GW | About 11 GW (41%) |
Total utility-scale battery capacity grew by roughly 10 GW in 2024, one of the largest single-year increases of any U.S. power resource. The detailed use-case figures, along with state and market breakdowns, are published in the EIA's File 3.4 (Energy Storage) and summarized in its analysis Utility-scale batteries are more commonly used for price arbitrage.
Batteries usually serve more than one role, and operators stack services to improve returns. The main non-arbitrage uses reported to the EIA are:
Based on the EIA shares, capacity primarily dedicated to arbitrage exceeded that primarily used for frequency regulation by roughly 4.5 GW, and frequency-regulation capacity was about 3 GW higher than capacity primarily used for balancing renewables.
| Market (end of 2024) | Battery capacity | Primarily used for arbitrage |
|---|---|---|
| CAISO (California) | 11.7 GW | 43% |
| ERCOT (Texas) | 8.1 GW | About 50% |
The two markets together hold most of the country's utility-scale battery capacity but reward it differently. California's steep midday-to-evening price swings, shaped by high solar penetration, support charge-low and discharge-high strategies, while capacity and resource-adequacy arrangements also value reliable multi-hour output. In Texas, an energy-only market with volatile real-time prices historically produced strong ancillary-service returns; as more batteries enter that market, returns from regulation have become more competitive and operators have shifted attention toward energy-market spreads.
Simple buy-low and sell-high dispatch is becoming harder to rely on. Rapid deployment means more batteries compete for the same low-price charging windows and evening price peaks, which can narrow spreads. Operators increasingly use optimization software that co-bids energy, reserves and regulation, and that accounts for battery degradation and forecast uncertainty, to stay above market-average returns. In practice, profitable projects tend to run integrated, risk-adjusted strategies that combine arbitrage with ancillary services rather than depending on one revenue line.
The EIA is scheduled to publish updated storage use-case data for 2025 as part of its next Annual Electric Generator Report release in 2026. That update will show whether arbitrage keeps its lead as newer markets in the Southwest, Midwest and Southeast expand, and how the mix of regulation, reserves and renewable-firming services evolves as the fleet grows.
For project developers and commercial buyers evaluating hardware, the practical takeaway is to specify battery storage systems with the round-trip efficiency, cycle life and communication controls needed to support stacked revenue services, rather than sizing for a single use case. GreenMore supplies containerized and cabinet storage for commercial and larger distributed projects; details are available under commercial energy storage batteries.
Arbitrage means charging a battery during periods of low wholesale electricity prices and discharging it back to the grid when prices are higher. In solar-heavy markets, charging often happens around midday and discharge during the evening demand peak.
No. Storage also earns value from frequency regulation, operating reserves, renewable integration and firming, peak shaving, and voltage or reactive power support. Most batteries report more than one use, and stacking services is what commonly improves project returns.
Both have high renewable penetration and large intraday price movements, which give batteries clear charging and discharging opportunities. They also have market rules that let storage participate in energy and ancillary-service markets. Other regions are now growing quickly from a smaller base.
It can. As more systems charge and discharge at the same times, price spreads can narrow. This is why operators combine arbitrage with ancillary services and use dispatch optimization, rather than relying on a fixed daily cycle.
Peter works with developers, installers and commercial buyers on battery storage sizing and revenue-oriented system design. He tracks EIA and wholesale-market data to help customers understand how arbitrage, frequency regulation and renewable integration translate into real operating value, and advises on specifications that support multiple revenue services.
Stay up to date with GreenMore. We share new BIPV solar tile releases, product and certification updates, and field notes from our projects — no fluff, just the things that matter to installers, distributors, and system integrators. If there's something you'd like to see covered, drop us a line — we read every reply.


Copyright @ 2026 GreenMore All Rights Reserved.  Network Supported
Sitemap / Blog / Xml / Privacy Policy