How businesses use cheap electricity
May 05, 2025
Australia's grid-scale batteries earned roughly AU$27,000 per MW in the twelve months to June 2026. The spread they were chasing, peak minus off-peak across the National Electricity Market, sat at AU$342 per MWh two years earlier. By mid-2026 it was AU$51. An 85% collapse in the one thing the business model was built on.
Over the same stretch a two-hour battery in Britain earned £93,000 per MW in October 2026, up 17% on the same month a year earlier and well above its £73,145 trailing-twelve-month average.
Both numbers are real, they describe the same technology in the same year, and what separates them is not cell chemistry or the price of a rack. It is how many separate line items on a customer's electricity bill the asset is allowed to touch. Australia's fleet sells into one market that has been arbitraged into flatness. Britain's fleet sells into four, and when the first one thinned out the other three grew.
For a business deciding whether to put a cabinet behind the meter in 2026, the question is no longer what the peak-valley spread is. It is how many of the four legs the site can reach, and what the cabinet has to look like in order to reach them.
What your electricity bill is actually made of
A commercial bill is not one price. It is four charges with different units, different clocks and different people setting them.
Energy is billed per kWh. It is the number everyone looks at and, for most commercial customers in Europe and North America, it stopped being the biggest one some years ago.
Demand is billed per kW, measured over a short window, usually the highest 15-minute average in the billing month. One bad quarter of an hour on a Tuesday morning sets the charge for the whole month, and under a ratchet clause it can set a floor under the next eleven.
Network charges are billed on capacity or on time-of-use energy depending on the country. Britain's DUoS red band runs 4pm to 7pm on winter weekdays at roughly 18p per kWh. China bills two-part tariffs with a separate capacity charge per kVA on top of the energy rate.
Policy and taxes sit on top of all three: VAT, the climate change levy, Germany's various Umlagen, China's renewable surcharge.
The reason to separate them is that a battery does not compete with the electricity price. It competes with whichever of the four lines it can move, and the size of that line varies by a factor of ten between markets.
A rate sheet makes it concrete. PG&E's E-19 medium general demand schedule carries a demand charge of $42.10 per kW across all twelve months. An 800 kW peak on that schedule generates $404,160 a year in demand charges before a single kilowatt-hour is billed. Cut 100 kW off the peak and $50,520 leaves the bill without anything being generated.
Line
Billed on
Typical share of a commercial bill
Can a battery move it
Energy
kWh, often time-of-use
40–60%
Yes, by arbitrage
Demand
Peak kW over a 15-minute window
20–50%, highest where capacity is tight
Yes, by peak shaving
Network or capacity
kW, kVA or time-of-use kWh
10–25%
Partly, via red-band avoidance
Policy and taxes
A percentage of the above, or per kWh
5–20%
No
Shares are indicative ranges across US, British, German and Chinese commercial tariffs and move with voltage level, load factor and country. US rate structures are searchable in the OpenEI Utility Rate Database, and average prices by sector sit in EIA's Electric Power Monthly.
Leg one: arbitrage, and a spread that arbitraged itself
The arithmetic is simple enough to write on a napkin. Gross margin per cycle is discharged kWh times the peak price, minus charged kWh times the off-peak price, and the difference is yours.
The formula is not the problem. The problem is that everyone with a battery is running it.
Australia is the cleanest case study because the data is public and the fleet is large, over 9 GW of grid-scale storage in the NEM by the second quarter of 2026. The average peak-to-off-peak spread fell from AU$342 per MWh to AU$51, a decline of 85%. The mechanism is not mysterious. Solar pushes daytime prices toward zero, every battery in the market discharges into the evening peak, and the evening peak stops being a peak. The spread was arbitraged by the assets built to capture it.
In June 2026 the 55 batteries operating in the NEM earned AU$17.98 million between them, about AU$2,000 per MW per month or AU$27,000 per MW annualised. A trader with perfect foresight would have captured AU$34.90 million more than the fleet actually did, a capture rate of 32%. Even with a perfect forecast the money is not there.
Duration shows where it went. One-hour systems earned about AU$3,000 per MW per month, two-hour AU$2,000, three-hour AU$1,000, and four-hour or longer AU$3,000 again. The middle of the curve got squeezed: long enough to compete with everyone else, not long enough to do anything they could not.
Britain shows the same decay in a different line item. Dynamic Containment, the fast frequency response product that carried a large share of battery revenue through 2022, fell from around £20 per MWh to below £1.50 per MWh by 2023–24.
China moved by regulation rather than by competition. Zhejiang's peak-valley spread was ¥0.8337 per kWh. After the province's October 2025 draft restructured the band ratio to 2.05 : 1.85 : 1 : 0.4 : 0.2 across peak, high, flat, valley and deep-valley, the effective spread fell to ¥0.5961, a 28.5% cut delivered by a document.
Market
Spread, 2024
Spread, 2026
Change
What happened
Australia, NEM wholesale
AU$342/MWh
AU$51/MWh
−85%
Battery fleet saturated the evening peak
Britain, Dynamic Containment
~£20/MWh
<£1.50/MWh
−93%
Product commoditised; revenue moved to wholesale and the balancing mechanism
China, Zhejiang
¥0.8337/kWh
¥0.5961/kWh
−28.5%
Band ratio restructured by provincial draft
Vietnam, 22 kV commercial
VND 2,208/kWh
VND 3,416/kWh
+55%
Circular 60 reclassified 22 kV users from manufacturing to commercial
The Vietnamese row is the exception and it is worth understanding why. The rate levels did not change. Decision 963/QĐ-BCT, effective 22 April 2026, restructured the time-of-use clock so that peak is now a single continuous 17:30–22:30 block Monday to Saturday with no Sunday peak, off-peak runs 00:00–06:00 daily, and the old morning peak is gone. Separately, a 22 kV customer that had been billed on the manufacturing schedule was reclassified onto the commercial schedule under Circular 60/2025, which widened its peak-to-off-peak spread from VND 2,208 to VND 3,416 per kWh. Same country, same year, spread up 55%, because a customer class moved.
Leg two: demand charges, the line most projects ignore
Here is what separates a demand charge from an arbitrage trade. The demand charge is written in a tariff schedule, and the schedule does not move when other people build batteries.
It is also measured brutally. Billing demand is the highest 15-minute average in the month, not the average and not the 95th percentile but the single worst quarter hour. A chiller bank starting at 09:12 on a Tuesday in July sets the number for July, and if the tariff carries an eleven-month ratchet at 60% or 80%, it sets a floor under the next eleven months too.
That measurement window makes peak shaving a power problem rather than an energy problem. A cabinet that delivers 125 kW for two hours will shave a 15-minute peak as long as the inverter ramps fast enough and the state of charge is where it needs to be when the spike arrives. It does not need much energy. It needs the right power rating and a control loop that reacts inside a second.
The value per kW is far higher than arbitrage. The same PG&E schedule that charges $42.10 per kW returns $505 per kW per year if the peak can be eliminated entirely, which in practice it cannot. Fifteen to thirty percent shaving is the realistic band.
Market
Rate schedule
Demand charge
Value of cutting 100 kW for a year
California, US
PG&E E-19, March 2026
$42.10/kW, all twelve months
$50,520
Washington, US
Puget Sound Energy, large demand
$18.88/kW summer, $11.67/kW winter
$1,888 across the summer months
Florida, US
Lakeland GSLD, FY2027
$11.60/kW
$13,920
Hubei, China
Two-part industrial, August 2026
¥42.0/kW-month at 1–10 kV
¥50,400
Germany
Small and medium industry contracts
No general demand charge
Zero, the leg does not exist
Germany is the useful negative case. BDEW's October 2026 price analysis puts the average small-to-medium industrial contract at 17.2 to 17.9 ct per kWh with no demand component, because the network charge is levied per kWh. A German factory can install the best-engineered cabinet in Europe and still have nowhere to put it, because the line it would have monetised never appears on the bill.
Hubei's fourth regulatory period, effective 1 August 2026, runs the other way. Two-part industrial customers at 1–10 kV pay ¥42.0 per kW per month in demand charges plus ¥26.3 per kVA per month in capacity charges, on top of an energy rate of ¥0.1263 per kWh. A 100 kW reduction in billing demand is worth ¥50,400 a year, which is more than most Chinese arbitrage projects earn per kW of installed capacity.
Leg three: demand response and capacity markets
Capacity markets pay for availability, not for energy. You are paid per kW of de-rated capacity for promising to be there, whether or not anyone calls.
Britain's auctions are the clearest public price signal and the signal is falling. The T-4 auction for delivery in 2027/28 cleared at £65 per kW per year. The T-4 for 2028/29 cleared at £60. The T-4 for 2029/30, held in March 2026, cleared at £27.10, a 58% cut in two auction rounds. The T-1 auction for 2026/27 cleared at £5.
Demand response in the United States pays better and varies more by region. Commercial and industrial programmes run $100 to $400 per kW-year depending on the market and the product, with fast frequency response historically paying several hundred dollars per kW-year, which is where the Australian and British fleets earned their early returns.
The catch is that this is the first leg to be competed away. It is the easiest to enter, needing no site works and no planning permission, just a controller and a contract, so it attracts the most capacity and the price falls fastest. Britain's revenue mix shows the migration. Ancillary services were 87% of battery revenue in 2020–22. By 2025 wholesale and balancing mechanism revenue was about 63%, ancillary services about 28%, and the capacity market about 10%.
Australia's frequency control market shows what the end of that curve looks like. Total FCAS cost across the NEM in the third quarter of 2026 was AU$5.1 million. In the same quarter a year earlier it was AU$73.4 million, and the 2026 figure was the lowest since 2016.
So leg three is real money today and a shrinking share tomorrow. The British capacity market rules and auction results are published, which makes it easy to check the trend before building a model on it.
Leg four: self-consumption, the leg no market can arbitrage away
The fourth leg does not touch a market at all. It is the retail price you no longer pay.
When a site generates solar and consumes it on site, every kWh avoided is worth the full retail rate: energy, network, policy, the lot. When the same kWh is exported it is worth the export tariff, which in most markets is a fraction of that.
The gap is the value of self-consumption, and it is why a battery on a solar site does a different job from a battery on a pure arbitrage site. A commercial rooftop without storage typically self-consumes 40% of what it generates, with the rest exported in the middle of the day when prices are lowest. Storage sized at 30% to 60% of daily PV generation pushes self-consumption past 80%.
The British DUoS red band makes this sharper than anywhere else. Between 4pm and 7pm on winter weekdays, distribution charges alone are around 18p per kWh. A battery that shifts afternoon generation into that window is not competing with the wholesale market. It is avoiding a regulated charge that no market participant can arbitrage away.
The ceiling on this leg is physical. It is roof area and inverter capacity. A site that has already covered its roof has no more self-consumption to sell, and the battery has to earn its keep on legs one to three. Sizing a rooftop array is its own calculation, covered in what size solar system do I need for my home and in the solar energy system range.
Annual value per kW of installed capacity. Demand bars assume full elimination of the billing peak at the listed rate. Arbitrage bars assume 330 cycles at 90% round-trip. Capacity market bars use the clearing price per kW of de-rated capacity. Self-consumption is excluded because its value equals the retail rate and is bounded by roof area rather than by market price.
What the hardware actually costs in 2026
Prices have moved a long way and the published numbers are not comparable to each other, which is where most budget conversations go wrong.
Market
100 kWh class
500 kWh class
1 MWh and above
What the figure includes
Britain
£400–700/kWh
£400–700/kWh
£350–550/kWh
Cabinet, PCS, commissioning, excluding grid works
United States
~$180/kWh
~$180/kWh
~$180/kWh
Installed, excluding interconnection upgrade
Vietnam
$190/kWh
$190/kWh
Not quoted
Liquid-cooled cabinet, installed
Brazil
~$102/kWh
Not quoted
Not quoted
783 kWh at 300 kW, turnkey
China
Not quoted
Not quoted
¥0.53/Wh floor
Two-hour LFP, lowest winning bid, July 2026
Read the Chinese row carefully. ¥0.5298 per Wh, the lowest winning bid for a two-hour LFP system in July 2026, is roughly ¥530 per kWh or about $74. It is a real number and it is a system price, but it excludes interconnection, civil works, commissioning and the transformer. A European or American project at $180 per kWh all-in is not being overcharged by a factor of two. It is buying a different scope.
The component curve is the thing worth tracking, because it moves independently of scope. Between 2020 and 2026 the cell pack went from about $150 per kWh to $80, installed system cost from $300 to $180, cycle life from 4,000 to over 6,000 cycles, and round-trip efficiency from 85% to 92%. The IEA's battery cost tracking puts the global learning rate at roughly 20% per doubling of cumulative capacity, which is worth reading before assuming 2026 prices are the floor.
Cycle life is the number that decides whether a project works. A cabinet rated at 6,000 cycles run once a day lasts sixteen years. Run twice a day it lasts eight, and the second daily cycle has to earn back its own capital. That is why Chinese project economics talk about two-charge-two-discharge and European ones mostly do not.
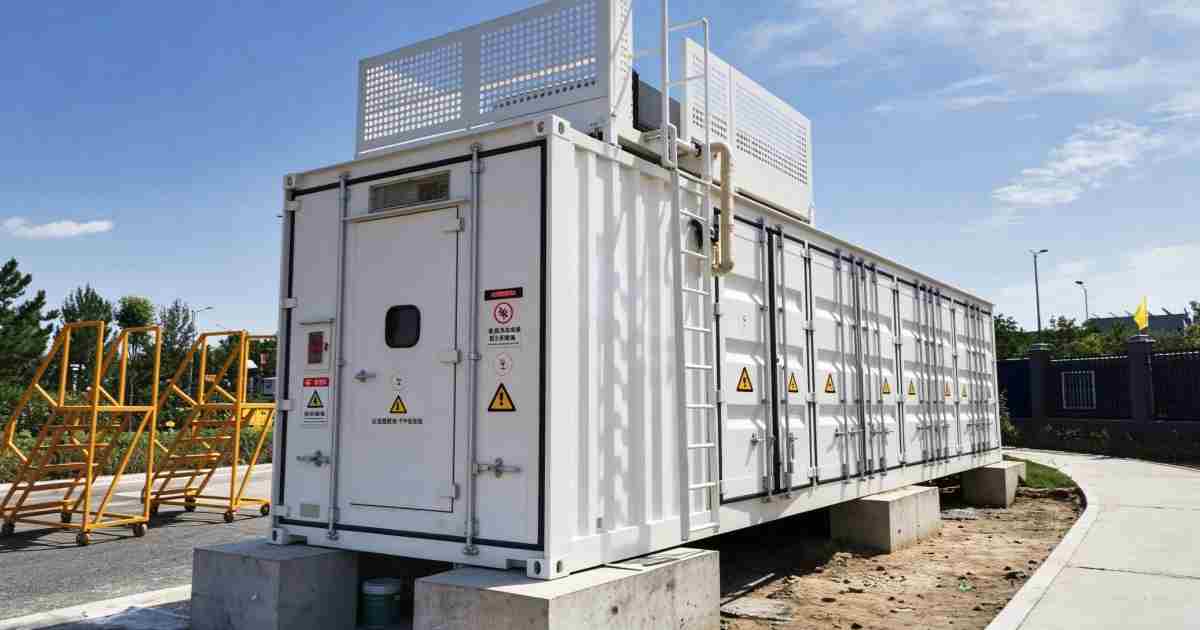
Outdoor enclosures add a separate line to the budget, and it is not a small one: thermal management, IP rating and condensation control decide whether the cabinet survives a decade on a factory wall. Outdoor energy storage cabinets and container systems sit at different points on that trade-off, and the air-cooled cabinet range is where most 100 to 500 kWh commercial projects land.
Four projects, four paybacks
Four real projects, four revenue mixes, four answers. None of them is a spreadsheet.
Site
Size
Capex
Annual value
Payback
What carries it
Manchester, UK, food processing
250 kWh / 125 kW
£140,000 at £560/kWh
£27,700
5.1 years gross, 3.8 after 25% AIA
PV self-consumption £6,800; peak shaving and DUoS £12,400; Dynamic Containment £8,500
Los Angeles, US, office
400 kWh / 100 kW
$260,000 net
~$90,000
2.9 years
Demand $60,000; arbitrage $18,000; demand response $12,000
Houston, US, manufacturing
2,000 kWh / 500 kW
$1.4m all-in
~$285,000
4.9 years
Demand plus arbitrage plus demand response
São Paulo, Brazil, factory
783 kWh / 300 kW
$80,000
~$53,500
About 18 months
Peak-valley arbitrage only, at a $0.273/kWh spread
Manchester is the case worth studying because the revenue mix is published and the mix is wrong for the hardware. A 250 kWh cabinet with a 125 kW inverter is a two-hour asset. Two hours is the right shape for arbitrage and the wrong shape for demand charges. The site earned £12,400 from shaving and DUoS avoidance and only £8,500 from Dynamic Containment, and that £8,500 came from a product whose price has since fallen further. A 250 kWh cabinet with a 250 kW inverter would have cost perhaps 8% more and earned more on the leg that actually pays.
Tax treatment matters as much as the engineering in Britain. The 25% AIA claim took effective cost from £140,000 to £105,000 and payback from 5.1 years to 3.8. Over fifteen years at a 7% discount rate the project carries an NPV of roughly £245,000 and an IRR of 18.6%.
Los Angeles is the opposite shape. Two thirds of the value comes from demand charges on a schedule that bills $42 per kW, and the system is sized at four hours because the office load is flat and the peaks are shallow but expensive. São Paulo is pure arbitrage at a $0.273 spread, which is why it pays back in eighteen months with the cheapest hardware on the list.
Note what is missing from the two American rows: the 30% federal investment tax credit that applied to purchased systems under section 25D expired at the end of 2025. A US project modelled in 2026 has to stand on its own cash flow, and both paybacks above are unsubsidised.
Where the model breaks
Market
Installed cost
Spread today
Payback today
At −30% spread
At −50% spread
Zhejiang, China
¥1.10/Wh
¥0.596/kWh
6.2 years
8.9 years
12.4 years
Vietnam, 22 kV commercial
$190/kWh
$0.134/kWh
4.8 years
6.8 years
9.5 years
São Paulo, Brazil
$102/kWh
$0.273/kWh
1.3 years
1.8 years
2.5 years
The table assumes 330 cycles a year, 90% round-trip efficiency, and no O and M, no demand charge value and no capacity market revenue. It is the pure arbitrage case, which is the case that fails first. The uniform cycle count is also why São Paulo reads 1.3 years here and about 18 months in Table 5: the real project runs a 22-working-day month, which is 264 cycles a year, not 330.
Five things kill these projects and four of them are not about the battery.
The spread moves and it does not move back. Australia lost 85% in two years. A project built on leg one alone with a 4.8-year payback becomes a 9.5-year payback at half the spread, which is longer than the warranty on most inverters.
The ratchet and the 15-minute window. A cabinet whose state of charge is wrong at the moment the spike arrives earns nothing that month, no matter how much energy it holds. Control strategy matters more than capacity, and it is the part buyers evaluate least.
Interconnection. Standard power transformers in the US are running about 128 weeks from order to delivery in 2026 and generator step-up transformers about 144, with large units out to four years. The American queue holds 2,061 GW of requests; of the capacity that requested interconnection between 2000 and 2020 only about 13% reached commercial operation. A storage project can be built in 18 to 24 months and still wait four years for permission to energise.
Cycle life and degradation. Six thousand cycles once a day is sixteen years. Twice a day is eight, and the warranty is usually written on throughput rather than on calendar time.
Policy. China's National Development and Reform Commission issued a directive in November 2025 stating that users participating directly in the market would in principle no longer be subject to government-set time-of-use tariffs. Zhejiang's 28.5% cut arrived as a draft. One document can remove a third of leg one, and no amount of engineering protects against it.
How to size it without overbuilding
Three constraints bind and they are not interchangeable. Power sets how much demand you can shave. Capacity sets how much energy you can shift. Interconnection sets how big you are allowed to be at all.
Start with the third, because it is the only one you cannot engineer around. Before a single rack is specified the site needs its transformer headroom and its connection agreement in hand. The preparation checklist for a commercial installation puts the connection survey first for exactly this reason.
Then the power rating, from the load profile. A two-shift factory with a sharp morning ramp wants a high C-rate, 1.5C to 2C, because the job is a fifteen-minute spike and not a four-hour shift. An office with a flat afternoon load wants 0.5C and four hours, because the peaks are shallow and the value sits in the duration. A cold store sits between the two and has to account for compressor cycling on top.
Then the capacity, from the daily energy. For arbitrage, size to the number of off-peak hours you can actually charge in, not to the peak hours you would like to discharge in. For self-consumption on a solar site, 30% to 60% of daily PV generation is the working range.
Manchester is the sizing lesson in one line. 250 kWh at 125 kW is a two-hour asset, and a two-hour asset cannot shave a fifteen-minute peak as hard as a one-hour asset of the same energy. The cabinet was right and the inverter was small, and the £3,900 gap between the two revenue lines is what that costs.
The practical rule for a first project is to size the inverter for the peak and the energy for the cycle, then check both against the connection agreement. If the connection caps you below the peak you need to shave, the demand charge leg is unavailable and the business case has to be rebuilt on arbitrage and self-consumption alone. Stacked battery systems and the wider commercial energy storage range cover the configurations that fit inside those three constraints, and our engineering team will size a first project against your actual tariff rather than a national average.
Frequently Asked Questions
Is peak-valley arbitrage still profitable in 2026?
In some markets yes and in others no, and the difference is the spread rather than the hardware. A two-hour system in Vietnam at VND 3,416 per kWh pays back in about 4.8 years on arbitrage alone. The same system in Australia at AU$51 per MWh would not pay back at all. Zhejiang's spread fell 28.5% in a single regulatory round. Before modelling anything, get the tariff the site is actually on, not the national average.
Do I need solar to make storage work?
No, but the revenue mix changes completely. A solar site gets a fourth leg, self-consumption at the full retail rate, which is the only leg no market participant can arbitrage away. Without solar, a commercial site is working with demand charges, arbitrage and demand response, and in Germany, where there is no general demand charge, that leaves two.
How is a demand response payment different from a demand charge saving?
A demand charge is a cost you avoid by not importing power at the wrong moment; the money never leaves the account. A demand response payment is revenue for promising to reduce load when the system operator calls, paid whether or not the call comes. The first is set by a tariff schedule and is stable. The second is set by an auction and has been falling, with Britain's T-4 capacity price going from £65 to £27.10 per kW-year in two rounds.
What size battery does a typical commercial site need?
Between 50 and 500 kWh for most sites, and the number comes from the load profile rather than the floor area. A 400 kWh cabinet at 100 kW suits an office with shallow afternoon peaks. A 250 kWh cabinet at 250 kW suits a factory with a sharp morning ramp. Getting the ratio wrong costs more than getting the total wrong, because a cabinet sized for duration cannot shave a fifteen-minute peak no matter how many kilowatt-hours it holds.
Why did Australian battery revenue fall while British revenue rose?
Australia's fleet sells into one market that has been arbitraged into flatness. The spread fell 85% and the whole fleet earned about AU$27,000 per MW annualised. Britain's fleet sells into four, and when Dynamic Containment collapsed from £20 to under £1.50 per MWh, wholesale and balancing mechanism revenue took over. British two-hour revenue reached £93,000 per MW in October 2026, 17% above the same month a year earlier.
Can I add storage without upgrading the transformer?
Usually yes, and it is the main reason behind-the-meter storage gets built faster than grid-scale projects. A battery that never exports, or exports within an existing export limit, does not raise the site's maximum import, so the connection agreement does not change. The moment the design includes export to the grid the site is back in the interconnection queue, and in the United States that queue is running four to five years for large projects.
P
Peter Lu
Energy Storage Product Manager, GreenMore
Works on commercial and industrial storage sizing, tariff analysis and the control strategies that decide whether a cabinet earns on demand charges or on arbitrage. Has been with the storage team since 2019.
Updated on November 17, 2026


 Network Supported